Growth can put more orders on the report while leaving less cash to work with. The ecommerce investment cycle starts when you commit cash to inventory, acquisition or retention and ends when the resulting contribution recovers the included costs. ROI.LIVE plans that cycle from observed customer behavior and stated assumptions, keeping revenue, contribution and cash in view.
Work through three decisions together: what a customer can fund, how long you can wait and how much demand the operation can fulfill. Use the same cost definitions across the report so the acquisition plan agrees with the cash plan.
If those inputs are still assumptions because the store has not launched, start with ecommerce prelaunch planning and collect evidence before expanding the budget.
Build the first-order economics
Start with net order revenue after discounts and expected refunds. Subtract product cost, payment fees, fulfillment, shipping subsidy, return handling and other variable order costs. The amount left before acquisition is the first-order contribution available under the model.
The breakeven acquisition calculator lets an owner reserve part of that contribution for overhead and profit. A cost equal to the entire first-order contribution leaves nothing from that order for those excluded obligations.
Decide whether later contribution can be used
You may be able to spend more than the first order contributes if repeat buying supports the decision. Use mature customer evidence, include retention costs and a downside case, and check that the business can fund the wait. If cash needs to return on the first order, build the acquisition limit around that constraint.
Choose the ceiling from margin, repeat behavior, cash and capacity. Businesses can have different operating constraints even at the same revenue size. A model that works for another store may ask yours to wait longer than it can afford.
Compare cohorts at the same age
Group customers by first purchase and measure net revenue and contribution at matching ages. Keep immature future periods blank or label them as forecasts. The cohort analysis guide explains how a maturity mismatch can create a false decline in customer value.
Keep all acquired customers in the denominator when estimating contribution per acquired customer. Looking only at repeat buyers would exclude the customers whose first purchase was their last.
A worked contribution model
From modeled revenue to acquisition capacity
Illustrative two-year model; the spending amounts below are assumptions.
Read the full explanation
This example is illustrative. A customer is expected to place 4.2 orders per year at $90 average net order revenue for two years. The revenue model is $90 × 4.2 × 2 = $756. That is revenue, not the amount available for acquisition.
Suppose the model assumes a 35% contribution rate before acquisition and retention-program costs, then $30 of retention cost over the horizon. Modeled contribution available before acquisition is $756 × 35% − $30 = $234.60. A $150 acquisition cost would leave $84.60 under those assumptions, before other excluded costs.
The result depends on the repeat rate, contribution rate, horizon and retention cost. It does not prove the next customer will produce that value or that $150 is an appropriate acquisition target for the business.
Add the timing of the cash
The same total can require a different funding wait
Cash commitments
Inventory deposits, acquisition and retention costs.
Timing variables
Supplier terms, settlement, returns and fulfillment.
Recovery record
Monthly cumulative cash, including the gap before payback.
Read the full explanation
The same total contribution can leave you with different funding needs depending on when it arrives. A slower-paying customer group needs more cash before recovery. Inventory deposits, supplier terms, settlement, returns and fulfillment costs can widen that gap, so put their dates into the plan too.
Build a monthly cumulative cash view rather than dividing a two-year value by an acquisition cost and declaring the business ready to scale. The email payback model shows how a group can produce substantial revenue while still failing to recover acquisition within the chosen horizon.
Plan seasonality from the business's history
Use actual weekly or monthly demand, contribution and stock records. Align movable events and note changes in product mix or prices. The seasonality guide gives a sample curve while keeping it separate from a universal ecommerce benchmark.
A low-cost acquisition period may be useful for building future demand, but only if the later contribution and cash timing support it. A peak quarter can still justify new-customer acquisition when the marginal economics and fulfillment capacity work. Avoid assigning every business the same quarterly role.
Schedule the work that must precede demand
Inventory, product pages, creative, approval, shipping terms and customer support must be ready before the campaign. The editable marketing calendar records those dependencies alongside the public date.
Keep contingency inside the approved total unless someone authorizes extra funding. Name who can reallocate the budget and what evidence they need. Your calendar should let the team see cash and stock limits before it promises customers more than the business can supply.
Test offers against contribution
Discounts can increase orders while reducing the amount each order contributes. The discounting guide includes a calculator and a worked comparison. Evaluate contribution per eligible customer, delayed returns and the cost of reaching the audience.
Do not infer permanent customer behavior from one short campaign. Observe matched-age groups and maintain the offer history. A promotion's immediate result and its later effect are different questions.
Present the plan with a lower-performance case
Name the condition that changes spending
Lower repeat purchasing
Recalculate contribution under that assumption.
More expensive acquisition
Inspect the contribution and cash left.
Later demand
Inspect the funding wait.
Operating response
Name the cash or contribution limit that reduces spending.
Read the full explanation
Show what you would do if repeat purchases fall short, acquisition costs rise or demand arrives late. Name the cash or contribution limit that would make you reduce spending. Deciding that in the model gives the team a rule to use when the actual results arrive.
The five-slide board template separates actual results, forecasts and requested decisions. Keep the source table and assumptions available so the board can inspect the calculation.
Review actual results without changing definitions
Compare cohorts at matching ages and periods with consistent cost treatment. Reconcile platform-attributed revenue with the order and finance systems. Preserve unattributed activity rather than forcing every sale into a preferred channel.
The email ROI guide distinguishes attribution from incrementality. A revenue-to-spend ratio is useful only when its label and denominator are correct; it is not automatically net profit.
Start with one cohort you can reconcile and the contribution from its first orders. Add the repeat contribution you have observed, then put it on a cash timeline. You will have a spending decision to assess against what the business can fund, and a record to revise when the next group behaves in a different way.
Choose the next question
 Growth economicsBreakeven CPA for ecommerce: calculate what an order can fund
 Marketing leadershipA five-slide CMO board-deck template
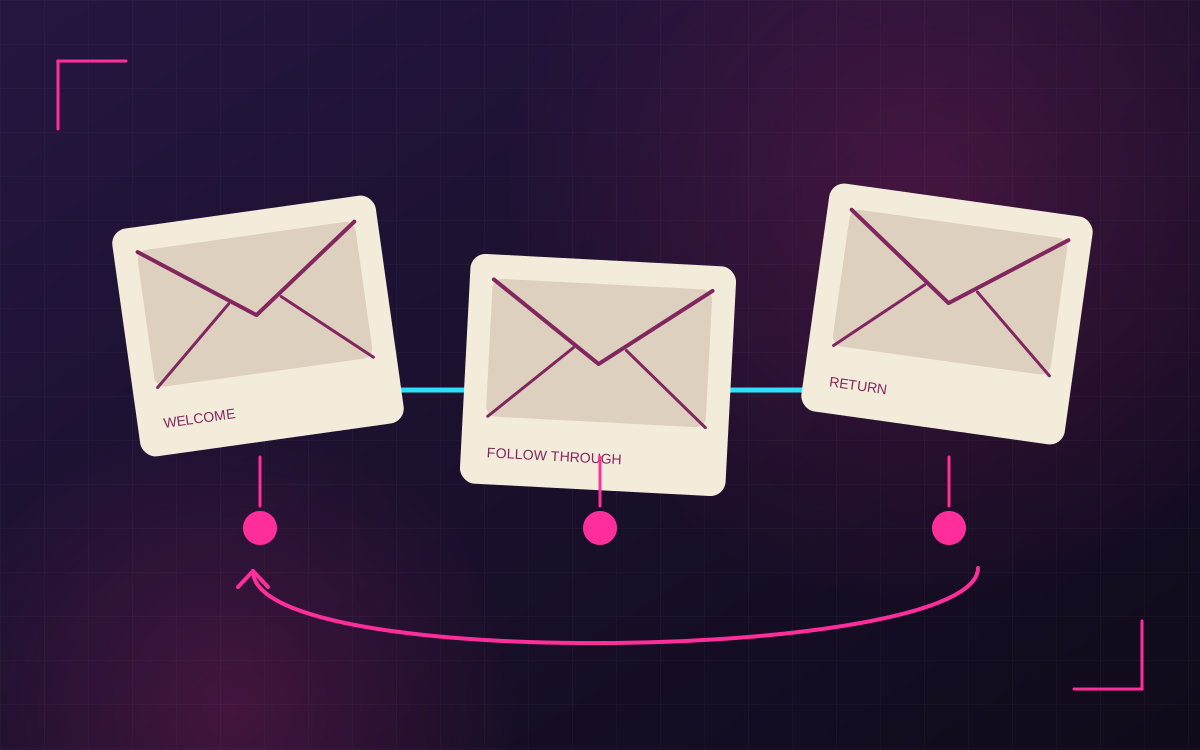 Email & retentionEcommerce LTV: compare customers at the same age
 Growth planningAn ecommerce marketing calendar tied to demand and capacity
- Growth planningEcommerce revenue seasonality: plan from your own demand curve
- Email & retentionEmail list payback: test a 90-day model with contribution
- Email & retentionEmail list ROI: measure contribution, cost and incrementality
- Marketing leadershipHow to present marketing ROI to a board
Questions owners ask
Should every ecommerce business require first-order payback?
No universal rule fits every business. Later contribution can support acquisition when mature evidence and cash capacity justify it; other businesses need a shorter recovery period.
Is customer lifetime revenue the acquisition ceiling?
No. Subtract relevant order and retention costs, retain the required contribution and account for uncertainty and cash timing.
Why does cohort age matter?
Older customers have had more time to repeat. Compare the same age or keep future estimates separately labeled as forecasts.
Should all fourth-quarter spending be retention?
No. Allocate according to demand, marginal economics, inventory and capacity. A fixed quarterly rule can miss profitable opportunities or fund unprofitable ones.
What belongs in the downside case?
Model lower repeat buying, higher acquisition cost, delayed demand, returns and the cash needed before recovery. State the condition that changes spending.
Method
This guide presents ROI.LIVE’s editorial analysis and worked methods. Numerical examples are illustrative unless expressly identified otherwise. No ranking, citation or business outcome is guaranteed.
Substantively revised September 8, 2026. Definitions, calculations, sources and internal destinations were reviewed for this edition.